Examining the US Modular Data Center Market Share and Competitive Dynamics
The competitive landscape for prefabricated data infrastructure in the United States is a vibrant and evolving arena, featuring a mix of global industrial giants, specialized engineering firms, and nimble innovators. An analysis of the Us Modular Data Center Market Share reveals a market that is both concentrated at the top and highly fragmented in the middle, with no single player holding an absolute monopoly. Market share is actively contested and is won or lost based on a company's ability to deliver on key value propositions: speed of deployment, reliability, cost-effectiveness, and technological innovation. The key competitors range from large, diversified technology and industrial companies that offer modular solutions as part of a broader portfolio, to pure-play specialists who focus exclusively on prefabricated data center products. As the market matures, the battle for market share is intensifying, forcing vendors to differentiate their offerings and forge strategic alliances to secure their position in this rapidly expanding and strategically vital sector of the US technology infrastructure.
The Dominance of Established Industrial and IT Giants
A significant portion of the market share is currently held by large, established multinational corporations with deep roots in power management, cooling, and IT infrastructure. Companies like Schneider Electric, Vertiv, and Eaton have leveraged their extensive engineering expertise, global supply chains, and long-standing relationships with enterprise and colocation customers to become leaders in the modular space. They offer comprehensive portfolios of pre-engineered and pre-integrated power, cooling, and IT modules that can be configured to meet a wide range of customer needs. Similarly, IT hardware giants like Dell Technologies and Hewlett Packard Enterprise (HPE) command a portion of the market by offering containerized and micro-modular solutions that are tightly integrated with their own server, storage, and networking equipment. These incumbents benefit from strong brand recognition, proven track records of reliability, and the ability to provide end-to-end solutions with global support, making them a preferred choice for many risk-averse large enterprises.
The Rise of Pure-Play Specialists and Innovators
Challenging the dominance of the industrial giants is a dynamic group of pure-play specialists who focus exclusively on the design and manufacturing of modular data centers. Companies like Compass Datacenters, GRC (Green Revolution Cooling), and numerous other regional players have carved out significant market share by concentrating on innovation and customer-centric design. Some specialize in ultra-efficient or highly customized builds, while others focus on specific niches, such as ruggedized modules for harsh environments or high-density solutions incorporating advanced liquid cooling for AI and HPC workloads. These specialists are often more agile than their larger competitors, able to innovate quickly and tailor their solutions to the precise requirements of a customer. Their go-to-market strategy often involves deep partnerships with colocation providers or directly targeting hyperscale clients with a compelling value proposition centered on speed, patented designs, and a flexible, partnership-based approach that resonates strongly with fast-moving clients.
Strategies for Capturing and Defending Market Share
In this competitive environment, vendors employ a multi-pronged strategy to capture and defend their market share. Technological innovation is paramount. Companies are investing heavily in R&D to improve the energy efficiency of their designs, increase power density, and integrate advanced liquid cooling solutions to cater to the growing demand from AI workloads. Supply chain mastery is another critical differentiator; the ability to source components reliably and manufacture modules without delay is essential for delivering on the core promise of speed. Strategic partnerships are also crucial. Modular manufacturers are forming tight alliances with colocation companies, real estate developers, and engineering firms to create a seamless end-to-end delivery ecosystem for customers. Finally, a clear focus on specific end-user segments—be it hyperscalers, enterprise clients, or the emerging edge market—allows vendors to tailor their products, messaging, and sales strategies to the unique pain points of their target audience, enabling them to build a defensible and profitable position.
➤ Featured Insights from Market Research Future:
الأقسام
إقرأ المزيد
The Cybersecurity Insurance Market is set to experience extraordinary growth, with projections indicating a market size jumping to approximately $45.29 billion by 2035. This represents a dramatic increase from $10.16 billion in 2024, showcasing a robust compound annual growth rate (CAGR) of 15.87%. The escalating frequency of cyber threats and subsequent regulatory demands are driving this...
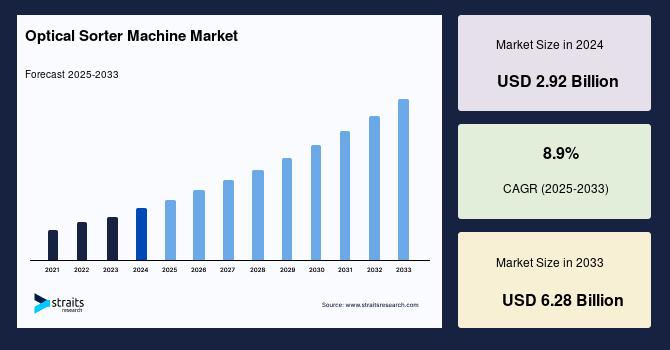
Optical Sorter Machine Market Overview A new report titled “Global Optical Sorter Machine Market Professional Report 2025-2033” has been added by Straits Research to its repository of research reports. The report analyzes and estimates the market on a global, regional, and country level. The report offers data from previous years along with an in-depth analysis from 2025 to 2033 on...
Mit der Erweiterung „Mega‑Schillern“ hält eine brandgefährliche Feuerstrategie Einzug in Pokémon TCG Pocket. Im Zentrum steht Mega‑Glurak X‑ex, ein Pokémon mit 220 KP und der Attacke „Wütender Brand“. Diese kostet drei Feuer‑Energien und fügt 100 Schadenspunkte zu. Sinkt die KP‑Anzahl von Mega‑Glurak auf 110 oder weniger, erhöht...
Команда PUBG: BATTLEGROUNDS с радостью поздравляет своих игроков с наступлением 2026 года и подготовила для них праздничный сюрприз — возвращение Весеннего феста 2025. В рамках этого события в игру вновь добавлены уникальные скины оружия, а также новые цветовые схемы и специальные предложения, предназначенные для всех участников. Особое внимание уделено обновленным улучшаемым скинам из...
The iconic checkmark seal once symbolized robust SSL security for online transactions. VeriSign built a business around licensing this trust mark to e-commerce sites, with studies showing it boosted consumer confidence and increased sales. Yet, the core SSL certificate market was slowing, prompting a strategic shift. VeriSign announced plans to vastly expand the seal's use to non-transactional...