Comprehensive Analysis of the Chiplet Market Industry Landscape and Competitive Dynamics
The Chiplet Market industry has established itself as one of the most transformative and rapidly accelerating sectors within the broader semiconductor, advanced packaging, and high-performance computing ecosystem. This industry encompasses a diverse range of modular semiconductor architectures, die-to-die interconnect technologies, and heterogeneous integration solutions that enable the assembly of multiple smaller dies—known as chiplets—into a single package, delivering superior performance, yield, and cost efficiency compared to traditional monolithic designs. The Chiplet Market Industry landscape is characterized by a complex network of stakeholders, including leading semiconductor manufacturers, foundries, OSAT providers, EDA and IP vendors, and hyperscale data center operators. At its core, the industry is driven by the convergence of rising demand for high-performance computing and AI, the economics of advanced node manufacturing, the growing adoption of modular design principles, and the push for energy-efficient semiconductor solutions.
The market was valued at USD 7.14 billion in 2024 and is projected to grow from USD 10.53 billion in 2025 to an extraordinary USD 510.3 billion by 2035, exhibiting a compound annual growth rate of 47.42% during the forecast period. Chip-on-Wafer (CoW) currently holds the largest share of the semiconductor technology segment, driven by its established use in high-performance computing and favorable integration capabilities. Chip-on-Substrate (CoS) is emerging as the fastest-growing technology, driven by demand for smaller, efficient chip designs and advanced packaging. 3D-stacked chiplets dominate the device type segment, while heterogeneous chiplets are the fastest-growing category. The competitive dynamics of the industry are shaped by several major players who collectively command significant market presence, including Intel, AMD, NVIDIA, Qualcomm, Broadcom, TSMC, Samsung, Micron, and Texas Instruments. Intel has focused on innovation through investments in advanced packaging technologies and announced a strategic partnership with a leading AI firm to develop next-generation chiplet designs. AMD unveiled its latest chiplet architecture designed to improve power efficiency and processing speed for data centers. TSMC expanded its chiplet manufacturing capabilities by investing in new fabrication facilities in Taiwan.
The industry is witnessing a significant shift towards standardization and collaboration, exemplified by the Universal Chiplet Interconnect Express (UCIe) Consortium, which aims to establish open standards for die-to-die interconnects. Strategic alliances among key players are increasingly shaping the competitive landscape, fostering innovation and collaboration. Regulatory considerations play a significant role, with the US Department of Commerce approving a $500 million grant for domestic chiplet manufacturing as part of the CHIPS Act initiative. As the industry continues to mature, it is likely to witness further consolidation and innovation, with emerging technologies and evolving client needs continuing to reshape the Chiplet Market landscape.
Explore More Like This in Our Semi Related Reports
Κατηγορίες
Διαβάζω περισσότερα
Season 2 Week 5 Challenges This article provides a detailed overview of all the challenges and objectives for Week 5 of the second season. If you enjoy the content, consider supporting us by buying a coffee 🙂 Quick donation: €2 Good support: €5 Super thanks: €10 Mega thanks: €25 Giga thanks: €50 King thanks: €100 In the latest update of Season 2,...
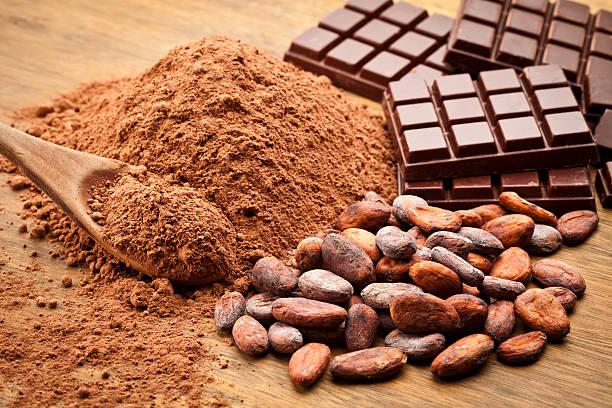
As per Market Research Future analysis, the Cocoa Powder Market Size was estimated at USD 24.95 Billion in 2024 and is projected to grow to USD 42.32 Billion by 2035, exhibiting a CAGR of 4.92% during the forecast period. The industry is witnessing sustained growth because of increasing demand for premium food ingredients and the widespread popularity of chocolate-flavored products. Cocoa...
Examining the global Residential Boiler market, covering comprehensive solutions for home heating and hot water, key technologies including condensing, non-condensing, and combi boilers, and the future outlook for residential boiler systems through 2035. The Global Residential Boiler Market represents the comprehensive landscape of home heating and domestic hot water technologies, providing the...
NBA 2K26 Season 2 is here, and its official soundtrack is already setting the tone for every virtual matchup. This 18-track seasonal playlist drops a high-energy blend of old-school heavyweights and fresh cross-genre sounds, built to match the intensity of the game. Legends like Jay-Z, Ms. Lauryn Hill, Outkast, Too $hort, and Kendrick Lamar go back-to-back with contemporary acts including Lorde...
The dynamics of Web Content Management Market Growth are being reshaped by a powerful wave of technological advancements that are redefining traditional business models. The current trajectory is heavily influenced by the global shift towards digital transformation, where automation and intelligent workflows are becoming standard practice. This evolution is creating a fertile environment...